What does it mean when a lender tells you the loan is fine, but the building isn't?
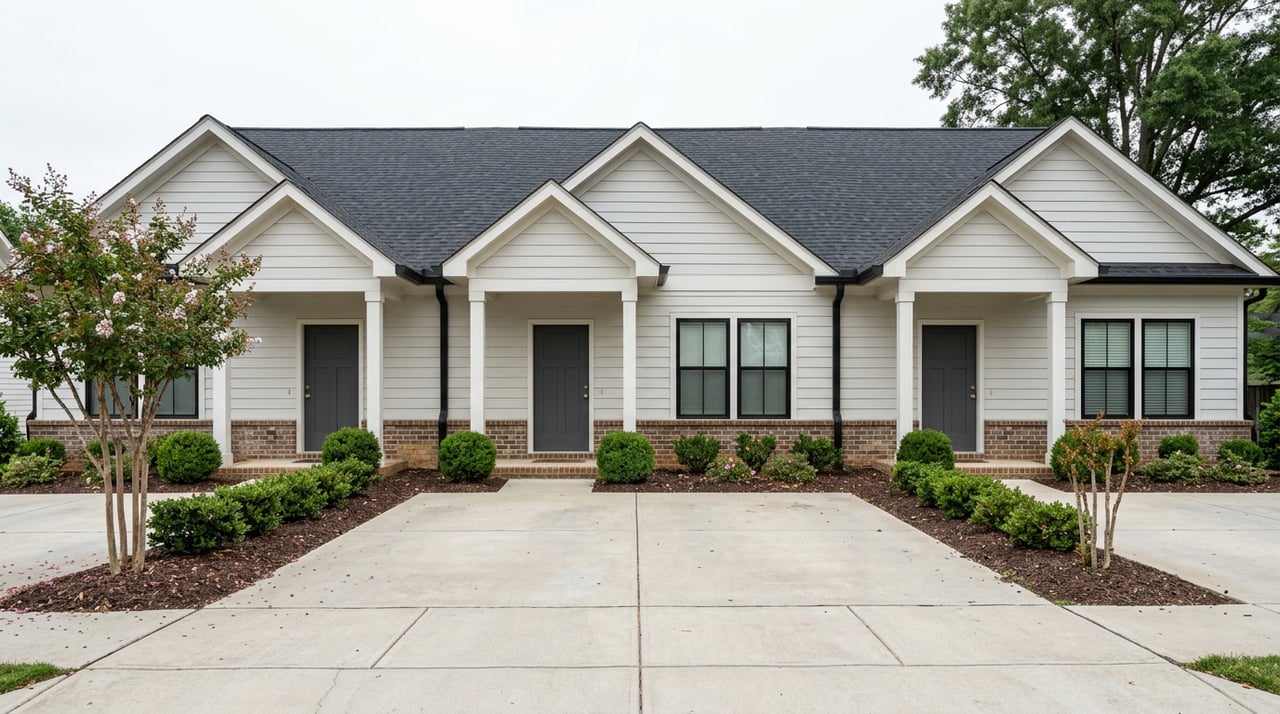
That's the question a lot of PCS families ask themselves the first time they fall for a listing in the Villas at Rudolphtown, the condominium pocket tucked into the Richview community near the corner of Richview and Memorial Drive. It's five minutes from I-24 at Exit 11, close enough to Fort Campbell that it shows up on every relocation shortlist, and priced well under the single-family stock a half mile away. On paper, it looks like the easiest kind of win for a buyer using a VA loan. In practice, the condo and the house next door are financed under two different rulebooks, and the gap between them is where offers fall apart.
One Neighborhood, Two Different Loan Products
Rudolphtown reads as a single neighborhood on a map, but it's really two housing products sharing an address. The Villas, built out between roughly 2005 and 2013, mix condos, single-level homes, and two-story townhomes under one HOA that handles exterior maintenance and grounds care for a modest monthly fee. A few streets over, Rudolphtown's single-family homes run the gamut from older ranch construction to newer builds, and that range shows up in the numbers. Zillow's mid-2026 value estimate for the broader Rudolphtown footprint averages $565,581, while Redfin's estimated take-home for one unit inside the Villas sits at roughly $344,000 today, up from a $262,500 sale back in 2018.
That spread is the point. The condo product is priced for exactly the buyer who is counting on tight closing timelines, and a straightforward VA loan. It's also the product where VA financing gets complicated in a way that has nothing to do with the buyer's credit, income, or service record.
Worth noting while you're studying the map: the city's most recent capital budget update left the Memorial Drive Extension improvements off the funded list for fiscal year 2026-27, which means the corridor Rudolphtown sits along will keep its current traffic pattern for at least another cycle. It doesn't change financing, but it's the kind of detail that shapes how a commute actually feels once you're living there.
How VA Condo Approval Works
Here's the part that catches people off guard. According to NewDay USA, a VA loan on a condo isn't approved unit by unit. It's approved project by project. The entire development has to clear VA review before any single buyer can close with VA financing inside it. FHA offers a workaround for this called Single-Unit Approval, which lets an individual condo qualify even when the building as a whole hasn't been certified. The VA has no broad Single-Unit Approval path. If the project isn't on the VA's approved list, your loan officer, your buyer's agent, and your own excellent credit score cannot get you to closing on that unit without a full project review.
This is where a status called "HUD Accepted" trips people up. VA Loan Network notes that some older condo developments carry this designation because they were FHA-approved before December 7, 2009, back when the VA automatically recognized FHA approval as its own. That policy ended. A "HUD Accepted" tag on the VA's list today is a historical record, not a live guarantee, so ask your lender to verify the project's current standing in the VA's own database before treating it as approved.
Here's a quick reference for what each status actually means once you're comparing units:
| VA Condo Status | What It Actually Means | What It Means for Your Closing |
|---|---|---|
| Accepted Without Conditions | Full project approval, no flags | Proceeds like any standard VA purchase |
| Accepted With Conditions | Approved, but the VA flagged something | Extra acknowledgment paperwork, timeline usually holds |
| HUD Accepted | Legacy FHA approval from before December 2009 | Lender must verify current VA standing before relying on it |
| Unaccepted | Never applied, or applied and was denied | No VA financing without a full project review |
What Actually Stretches the Timeline
If a project isn't accepted and your lender has to request a full review, plan for it to add real time. Industry guidance puts the realistic range at four to six weeks when the HOA has documents ready and management is responsive, stretching to eight or twelve weeks if paperwork has to be gathered piece by piece or the regional loan center is backed up. That review is essentially due diligence the VA is doing on your behalf before it guarantees a loan inside that community.
One detail lands especially hard for military buyers. Part of what the VA checks is whether the HOA's rules allow reasonable owner rentals. Smaller developments sometimes restrict rentals but it's also exactly the kind of clause that can keep a project off the VA's approved list. For a family that might need to rent out a home on short notice because of a future PCS order, that same restriction cuts both ways.
Timing matters more than it might seem. Clarksville's broader market was running a median days-on-market of about 75.5 as of March 2026, already down from the year before. A several-week condo approval delay isn't a rounding error against that window. It can eat a third of your closing timeline, sitting entirely outside your control.
The VA is underwriting the building before it underwrites you. If the building isn't ready, neither is the loan.
Four Things to Check Before You Write an Offer
- Search the VA's condo report yourself, before you tour. Go to the VA's official condo lookup and search by project name. Don't rely on a listing description or an HOA manager's memory of an old approval.
- Confirm the status is current, not historical. If you see "HUD Accepted," ask your lender to verify it against the live VA standard before you treat it as a green light.
- Ask for the HOA's governing documents early. According to Direct Mortgage Loans, rental restrictions factor into whether a project stays approved or ever gets there. Reading these before you're under contract saves you from discovering a dealbreaker during underwriting.
- Build review time into your contract if the project isn't yet approved. If your lender has to initiate a project review, add contingency time that matches the eight-to-twelve week range rather than hoping for the best case.
A Few Questions Worth Asking Your Lender
If the condo isn't VA-approved, can I just switch to a conventional or FHA loan instead? Sometimes, and FHA in particular offers its own Single-Unit Approval path that the VA doesn't. But switching loan types mid-contract changes your down payment math and your funding costs, so it's worth confirming eligibility for both before you're locked into a specific unit.
Does a past VA denial mean the building can never qualify? Not permanently. Veterans United describes a one-time VA condo waiver process available to veterans in specific circumstances when a project was reviewed and denied within the past year. It's a narrow path, and it's worth a direct conversation with your lender rather than assuming the door is closed.
Who pays for the project review if one is needed? The VA itself doesn't charge for the review, but some lenders charge a document processing fee and some HOAs charge to compile the package.
Rudolphtown's mix of condos and single-family homes is one of the things that makes it a genuinely flexible place to land near Fort Campbell, whether you want a low-maintenance property or more room to grow. The flexibility only works in your favor if you know which financing rules apply to which product before you fall for a specific address. If you're weighing a Villas condo against a single-family option elsewhere in Rudolphtown, or you need to understand what your current home would sell for before a PCS move locks in your timeline, Meg Pritschet can walk through both sides with you. Get your free instant home valuation and start the conversation with real numbers instead of assumptions.
This article is general information, not legal, tax or financial advice. Consult a qualified professional about your situation.